Category: Uncategorized

  • Meet our grads
    Jason Gu

    Studied: Bachelor of Actuarial Studies, Bachelor of Commerce
    Joined Taylor Fry: February 2019
    Location: Sydney
    Home team: Analytics

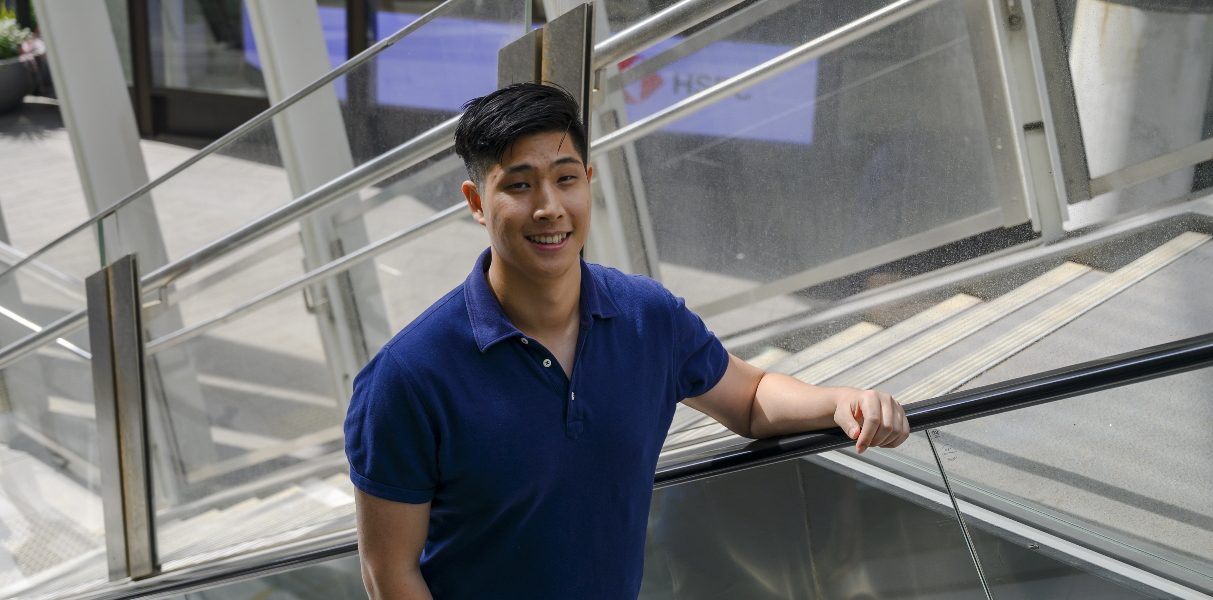
    Jason’s definitely answering a client email …

    How did you feel walking in the door on your first day?

    Nervous! But also excited to meet the other grads and more junior staff, and hoping we’d get along. I’d heard there were lots of PhDs in the company, so my perception was that Taylor Fry was a place full of smart people. And it’s true! That was intimidating at first, but everyone’s so supportive and approachable, even up to senior principal level – and I’m glad I can work in a place with so many experts in their field.

    Did anything surprise you?

    I was surprised by how many people came from diverse backgrounds – like me with commerce –although these were mainly in quantitative areas such as physics and chemistry, so I guess that part was to be expected. I was encouraged and inspired that these people were pursuing an actuarial career. I didn’t feel so alone, because there were people who had gone before me.

    What did you learn from our buddy system?

    It was great to have a buddy to help with fitting in early on in those first few weeks – someone you could ask silly questions and not be judged for them, like how to fix the printer when you cause a paper jam.

    It was quite different from having a mentor at uni, where everyone had fairly similar stories – they were the same age as me, with the same experiences, all studying actuarial degrees, and even from a select few schools.

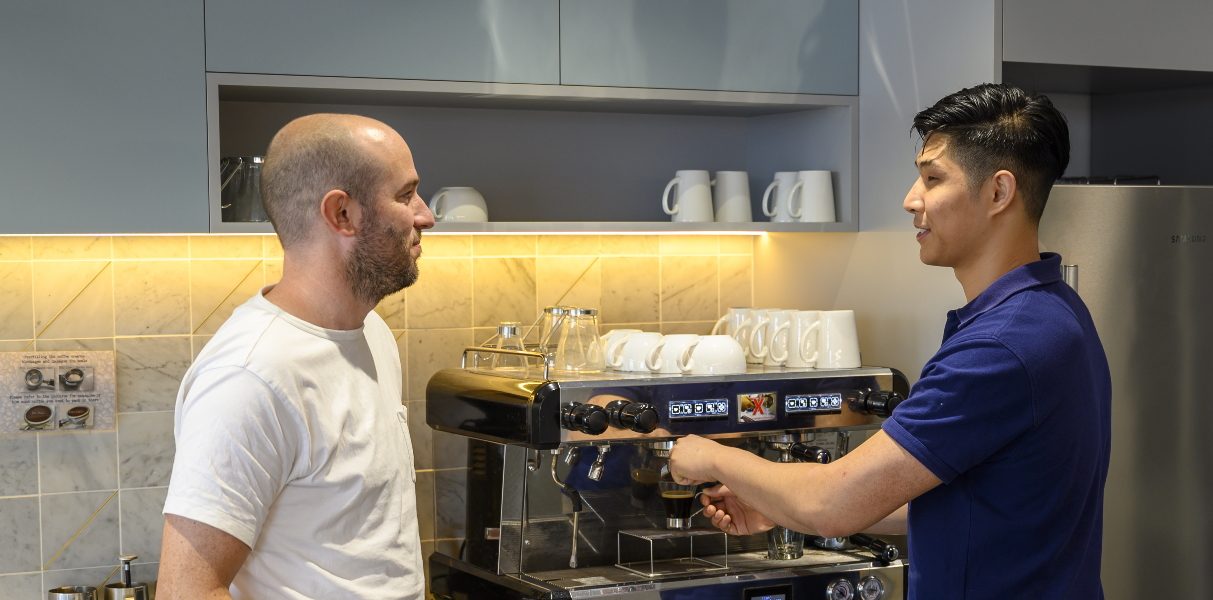
    My buddy Ian Hutton has a few more years of experience than me, he’s married and has kids, and he comes from a different career entirely – he was a musician previously. It was good to get to know him and his aspirations, why he decided to become an actuary and take on the role. The diversity was refreshing and he broadened my view considerably. He also taught me how to make good coffee!

    “He also taught me how to make good coffee!”

    Will Jason’s coffee meet Ian’s exacting standards?

    Were you able to sample various teams?

    Yes, my home team is analytics, but I found myself working more regularly with the general insurance team because I was placed where the resources were most needed at the time. I’m happy because I’m learning a lot and the work is quite diverse, from valuations for a multi-line insurer to workers compensation for a self-insurer – the liabilities for these are very different.

    I’m looking forward to my rotation back to analytics at some point to experience the different workflow. It tends to be more high pressure, with ad hoc demands and sprints to complete tasks. I’d like to be exposed to that and take on the challenge! That way of working differs from valuations for general insurance, where the groundwork has been laid out in the past and it’s a continuing piece of work, with adjustments made according to issues the company faces.

    I’m also interested in our social sector projects, where governments are looking for the most effective way to spend money to solve a problem. Our job is complex and there are a lot of factors to consider when deciding how to go about the analysis. You need a holistic view of the many influencing variables flowing in and out of that environment. If you try to fix something, you can expose another problem you may not have accounted for. The prospect of this challenge is incredibly interesting and exciting. Luckily, I’ll be able to sample all of these areas as part of our grad rotations.

    How does the knowledge you’ve gained formally compare with your on-the-job learning?

    At work, I learn to apply the more formal education. On-the-job learning is more naturally reinforced because you’re dealing with real-life situations that happen every day. It’s easier to take on knowledge when people around you explain and show you in a tangible, practical way. You get a sense of what’s important and what people care about, versus what’s nice to know.

    I draw on certain parts of my formal university knowledge to help me complete a particular task or project – but it’s the accumulated knowledge from different jobs that helps me build on it and continue to learn.

    Is this what you meant when you said climb the corporate ladder?

    Is the consulting environment what you expected?

    It’s more or less what I expected because I had completed my internship as a consultant with a large data science company, then had a part-time consulting role with a small software company. Taylor Fry seems to have the best features of those two different environments – the benefit of being recognised in the actuarial space as well as the agility of a smaller company, such as more autonomy and flexibility. My experience in both those roles was incredibly beneficial in preparing me for the demands and responsibilities of consulting at Taylor Fry.

    What’s the Taylor Fry uni case challenge and how were you involved?

    We were invited by The Actuarial Society of UNSW to host a case competition, where teams present their solutions to a hypothetical business problem. Alongside our parent company, Qantas, myself and fellow grad Thomas Zhou created a problem centered on a frequent flyer program, and later formed part of the panel judging the final four teams at an evening event at our Sydney office.

    It was such an interesting exercise and much harder than I had anticipated. It was a lot of work for the two of us to come up with a question and all the supporting data that reflected Taylor Fry – who we are, our values and what we stand for as a company. We had some great input and guidance from senior people, who gave up their time to help with setting the direction, tips on education and advising on data, as well as assistance with the formatting, branding and wording of the final package.

    We had more authority to drive the direction of the project than usual, so that was a very different experience for Thomas and me, and we felt the responsibility to achieve a good result. We really wanted to be proud of it.

    We had more authority to drive the direction of the project than usual

    I was pleasantly surprised by how it all turned out. It was a fun night. The students presented their question passionately and enthusiastically – they really threw themselves into it. And I was just so happy people actually wanted to answer our challenge and do it!

    Looking back over the year, how have you changed?

    I’ve become more organised, – I’ve had to! The commitment to full-time work means I plan and appreciate my free time much more, compared with being at uni, where I had two-day timetables. In between work and studying for Part 3s [the final step in becoming an actuarial fellow with the Actuaries Institute], I’ve taken a keen interest in overseas travel, as well as exploring more of Sydney and taking day trips. I’ve even taken up snowboarding!

    Has the experience altered your perception of being an actuary?

    My idea of being an actuary changed when I became aware of the need to consider consequences, that when you analyse data, the results you come up with can have a range of effects on business and people. You have to look quite deeply into a business problem and its environment in order to do that job well, and it’s a skill I still need to work on. But it’s also something that accumulates and develops over time.

    How would you like to see your role evolve?

    I want to continue gaining a broad range of experience, learning more and seeing how everything works – how modelling techniques are applied, and how different problems are solved with different approaches.

    Analytics and the social sector particularly interest me because the work has the potential to have a profound impact on people and society. For instance, providing insight into society’s most vulnerable children and their families enables government to develop new policies and programs with the possibility to improve many people’s lives.

    Analytics is a growing field, too. There’s lots of opportunity for people who can combine it in business, and actuaries fit well into this category. They can also complement their commercial sense with their social conscience, and I’d like to be part of that.

    Want to know more about our program? Head over to our graduate program page.

  • Taylor Fry achieves new ISO 27001 standard

    Taylor Fry has achieved the highest standard of best practice in the industry for its information security management system. The internationally recognised ISO 27001 certification is the culmination of a two-and-a-half-year transformation program within the firm, led by IT manager Thomas McCosker.

    “Being awarded this ISO 27001 standard provides our clients with the confidence to deliver us the rich and often sensitive data sets we need to produce work that ultimately helps them make effective decisions,” Thomas says.

    “It signals we have a mature approach to data security in the provision of our actuarial and analytical services, controlling how we receive, transmit and manage all of our data. There’s not a single part of our IT processes and technology this standard doesn’t touch.”

    Taylor Fry Principal Hugh Miller agrees the certification shows an increasing maturity of the company and says, “It reflects our underlying growth in the number and types of complex jobs we’re asked to do by clients.

    “Our corporate clients benefit from the high standard of data security we’ve had to develop for some of our modelling of highly sensitive government datasets. Implementing information security in a way that ensures security but enables rapid insights is not an easy task.”

    For the three-year certification, Taylor Fry adheres to more than 100 controls, or requirements, and demonstrates a method for implementing each, such as a risk management framework and defined, measurable objectives for our information security program. A mini surveillance audit will be conducted in one year and again in two years, with a full audit completed at the end of the three-year term.

    Thomas adds, “This is recognition we have achieved our IT and data transformation goals, helping to prepare us for information security in the present and setting the framework for us to respond to threats in the future.”

  • Seeing the forest for the analytics trees

    Our models are often built on the high-quality data that we can see, but ignore valuable information that falls outside our usual data collection. Hugh Miller unpacks this idea and analytics work more broadly in his latest column for Actuaries Digital.

    Recently I was invited to a meeting of the Collaborative Partnership, which aims to improve work participation for people with  physical or mental health conditions, by taking a cross-system view. There are some good resources there if you are interested in understanding the ways that different supports are given (through workers’ compensation, insurance and welfare).

    More broadly, the experience reminded me that analytics work is often very good at optimising the ‘known universe’ and often incredibly poor at providing insight outside that universe. For example, in workers’ compensation, a large amount of detailed modelling has been done to understand how injured workers move through the compensation scheme, but there is much less known about what happens once their compensation payments stop. Do they return to work? Or drop out of the workforce and not return? Do they have extended spells on welfare benefits? Or rely on insurance payouts?

    Analytics is often better at optimising the ‘known universe’ than providing insight beyond it

    This type of knowledge gap occurs in all sorts of analytics contexts. For instance:

    • Significant time and effort is now spent on monitoring sentiment from social media, which allows rich detail and insight to be generated on an interesting (but ultimately not entirely representative) portion of the population. Views beyond social media, which are harder to monitor, can be neglected. The gap between digital and non-digital is a consistent area where analytics models are incomplete; digital advertising is likewise a more measurable than traditional advertising spend but usually provides an incomplete picture of the customer base.
    • Insurers can have sophisticated models for certain sales channels (e.g. powerful demand estimates for online quotations) but have relatively crude approaches to other channels. For many years, group life insurance suffered in this fashion. It represented a significant portion of an insurer’s policies but had many unknowns and limited ability for the insurer to understand and manage their underwriting and risk profile.
    • Banks can be incredibly detailed in their understanding of a customer, to the extent that the customer’s accounts, credit cards and loans are bundled with the one bank. But a customer will often have accounts or products with other banks too, leaving a major hole in the understanding of a customer.
    • Government programs (such as housing programs) often cater to a particular cohort of people, for which the characteristics and needs can be well understood. But there will also be people just outside the eligibility of a program who have similar needs, which are sometimes met in other ways. This ‘latent demand’ is potentially invisible to government without significant work.

    Such myopia creates an obvious opportunity to investigate the ‘known unknowns’. While these are, by definition, harder to get right, there are some useful ideas that can help.

    1. A simple but robust answer to a big question can be more useful than a detailed answer to a small question

    Often there are ways to attack the bigger question, for example through using targeted surveys or conducting other research. Such evidence will not be as cutting edge as detailed modelling of the ‘known’ systems, but will enable broader and better questions to be answered. This type of thinking may affect how analytics projects are prioritised.

    2. Partnerships are possible

    In government, increasing use of data linkage is improving our understanding of how people move between systems, or potentially fall through the cracks. For corporates, data partnerships are possible to address similar sorts of cross-system questions, assuming appropriate privacy safeguards and consumer communication are in place. Vertical integration for companies can also achieve a broader customer view.

    3. The biggest risks can lie outside the system

    In the banking example given above, the risk of a customer leaving is significantly higher if they have accounts with other providers. A churn model that does not attempt to explore this risk is missing a trick.

    4. Models are getting better

    While the true status of a customer outside known datasets may be unknowable, it can often be inferred probabilistically from what is known. In such cases, it’s possible to meaningfully talk about the entire population despite the narrower scope of a dataset. For example, mortality rates attached to group life insurance must still be a legitimate subgroup of population-wide mortality, which is well-understood.

    We may never completely solve cross-system gaps. However, by thinking through how pieces fit together, we can reduce the risk that a model carefully built on main company databases becomes quickly outdated as the external environment evolves.

    As first published by Actuaries Digital, 7 November 2019

  • We need to talk about interpretable machine learning and embracing robust experimentation

    How can machine learning models be easy to understand and accurate? Why is it dangerous to listen to the HIPPO?

    Amid the glacial wilderness of Anchorage Alaska, some of the greatest minds in the data world gathered to talk hot topics at the 25th Association for Computing Machinery Special Interest Group conference on Knowledge Discovery and Data Science – or KDD for short. Peter Mulquiney, Jonathan Cohen and I braved the wild surrounds to take in the lively discussions.

    KDD bills itself as the premier interdisciplinary conference in data science and, judging by the list of attendees and impressive talks at this year’s event, that description felt pretty apt. Speakers from Google, Baidu, Alibaba, Amazon, Apple, Microsoft, NASA, LinkedIn, Facebook and many leading universities entertained the 3,500 visitors from around the world.

    Truly interdisciplinary, the streams covered several techniques. These ranged from deep learning, reinforcement learning, natural language processing and time series analysis to causal discovery, explainable AI, adversarial learning methods, graph theory, automated machine learning and recommender systems. Their applications were in areas spanning health, transportation, conservation, social impact, epidemiology, education, ecommerce, marketing and finance to name a few.

    Among all of this detail and choice, some main themes emerged, including the continual rise of deep learning, the incredible scale and use of data science in the leading Chinese tech companies and the importance for AI decisions to be ethical and fair. Above all, two themes dominated much of the discussion and are relevant to much of what we do: the need for interpretability in machine learning, and the importance and difficulty of establishing causal relationships.

    For some, the conference was polarising

    The need for interpretability in machine learning

    A common, and often genuine, criticism of many machine learning solutions is their ‘black box’ nature: users feel unable to adequately explain or interpret the outputs they produce. This lack of understanding has implications for fairness and trust in the model, potentially hiding unwanted or erroneous relationships the model has learned and which may have significant consequences for end users. Tackling the problem of interpretability is an active and popular field of research, as shown by the numerous talks on the subject – including a full day of (well-attended) tutorials and workshops dedicated to explainable AI!

    Keynote speaker Professor Cynthia Rudin, of Duke University in North Carolina, stood out among the talks of new and varied deep learning architectures and implementations. She chose instead to ask the question, Do simpler models exist and how can we find them?, arguing that the trend toward more complex models is neither necessary nor helpful. Presenting her research, she showed the conflict between interpretability and performance – where either the models are accurate but difficult to make sense of, or easy to understand but prone to error – is not as stark as many assume, and how simple-yet-accurate models can be found for many problem domains.

    This sentiment was echoed by Rich Caruana, of Microsoft Research in Washington, in his talk Friends don’t let friends deploy black-box models: the importance of intelligibility in machine learning. He discussed the need for model interpretability, particularly in the presence of confounding variables. Citing examples of machine learning failures in the health sector, he emphasised the importance of understanding the relationships being learned by the model, and ensuring these are reasonable and reflect the available domain knowledge – and correcting where they don’t! He promoted the use of simpler model structures, where these relationships are more easily observed and modified, as a more interpretable and accurate approach.

    For those of us familiar with the humble yet powerful generalised linear models, these arguments in favour of interpretable and controllable models felt all too familiar – a refreshing vote of confidence for the value of this accurate modelling approach. Deep isn’t always best!

    The importance and difficulty of establishing causal relationships

    Causal modelling was a hot topic at KDD 2019. Data is increasingly used to optimise business decisions in areas such as personalised marketing, next-best action, product design, pricing and user experience. Behind these decisions is a simple question of causation: given a set of competing options to choose from, which one will lead to the best outcome? The statistically sound approach would be to answer this through randomised controlled experiments (also known as A/B tests), when possible. Speakers from Microsoft, Outreach, Snap Inc. and Facebook discussed the importance, challenges and pitfalls of conducting these kinds of experiments individually and at scale.

    Providing a great overview of the topic, guest speaker Ronny Kohavi shared his experience from 14 years leading Microsoft’s experimentation team and, before that, as head of Amazon’s data mining and personalisation team. In his talk, Trustworthy online controlled experiments and the risk of uncontrolled observational studies, he discussed the dangers of relying on opinion or non-causal analysis as the basis for change – such as HIPPO (highest paid person’s opinion), observational studies and natural/non-randomised experiments.

    50 shades of blue? Experimentation can be very revealing

    Humans, he concluded, are generally poor at assessing the value of ideas and, to illustrate the point, Ronny shared some Microsoft statistics: hundreds of new ideas are tested –  using randomised controlled experimentation – every day at Microsoft, with the belief they will add value, and yet only one-third of these meet even their most basic targets and only 0.02% significantly improve upon their most important engagement metrics.

    As further proof of the value in randomised controlled experimentation, he highlighted a well-known event at Google a few years ago. After noticing two different shades of blue font were being used for a sole purpose, the data science team decided to unify and adopt a single colour. To determine which colour drove the highest user engagement, they tested 41 different shades of blue. The demand for data analysis in testing such ‘miniscule design decisions’ – seeming to favour engineers over designers – was cited by Google’s head of design at the time as a reason for his resignation. Yet the experiment led to a US$200 million boost to annual ad revenue.

    With many examples why randomised controlled experiments should be conducted, Ronny also discussed the challenges and pitfalls they present. One key challenge was gaining agreement across Microsoft, he said, on what ‘success’ truly means, in the form of an Overall Evaluation Criteria (OEC).

    Defining the right OEC is critical, he added, otherwise the decisions made will not be optimising the overall success of the business. A good OEC should rely on short-term metrics, which allow it to be readily observed, and those metrics should be predictive of longer-term value (such as customer lifetime value).

    Other pitfalls often lie in the execution of experiments, with Ronny highlighting the need to be wary of common issues such as sample ratio mismatch (an unexpected difference in treatment and control population sizes), novelty effects and poorly designed metrics. At Microsoft, A/A tests (where the treatments are identical and expected to yield identical results) were proposed to safeguard against flaws in experiment design and measurement. In addition, a broader set of robust monitoring practices were carried out, including raising alerts when things look too good to be true and not just when they are going poorly.

    So what does all this illuminating discourse mean in practice? Here are our KDD takeaways that we’re going to be applying back home:

    1. There is value in simplicity. Strong arguments support using simple, interpretable models in practice. Not every problem needs the latest deep-learning solution. Interpretable models can be deciphered and explained. They also provide insight and trust, the value of which should not be overlooked. Any predictive performance costs are likely to be much smaller than perceived.
    2. Invest in experimentation. Randomised controlled experiments will generally provide the best measure of the effect of changes or interventions, but care must be taken to ensure they are well designed and executed. Human judgment and observational studies are inherently tainted by bias and confounding factors, and so are poor substitutes when it comes to picking winning ideas. A good experimentation culture has the potential to prevent bad ideas being adopted, and highlight great ideas that might otherwise have been missed.
  • Forecasting future outcomes – Children of the revolution

    Amid the chaos and fear of our information-saturated world, with its ever-expanding data sets that access many aspects of our lives, is the ability to harness the predictive power of that data for social good. Peter Mulquiney explains how actuaries are leading the way and why young people are key.

    For many decades, federal and state governments have focused on improving the care of our most vulnerable citizens. This involves many government services, including justice, income support, public housing, healthcare, education and child protection.

    In a 2018 paper for the Actuaries Institute’s The Dialogue, Taylor Fry Principal Hugh Miller argued that pressure for these services to be more effective is triggered by fiscal demands, heightened expectations on measurement and improved longitudinal data.

    The paper, entitled People, projections and payments: a look at modern government service delivery, suggested actuaries have a role to play here – particularly in using data to inform policy.

    The Forecasting Future Outcomes report 1, a NSW government paper released in July, which studied the individual pathways of social service use for all three million people aged under 25 in NSW, is a good example of this.

    The Their Futures Matter reform

    The groundwork for the Forecasting Future Outcomes report began back in 2015, when an earlier report into out-of-home care in NSW found that, despite increased government spending on social services, the number of children in foster care had doubled over the past 10 years. At the same time, it found the long-term outcomes for these children remained poor with high levels of unemployment, incarceration and mental health issues as adults. That report also found that while the current system responds to immediate crises, such as a report to the child protection hotline, it failed to do enough in the area of prevention.

    In response, a unit was set up – now called the NSW Stronger Communities Investment Unit — to implement the Their Futures Matter reform, with responsibility to do more in the area of early intervention for vulnerable children. The idea was that if we invest money now to improve the lives of vulnerable children, we will not only improve the lives of those children but we will save money in the long term, as those children become better integrated into society and so less reliant on social services.

    The reform also emphasised the need to give greater weight to data and evidence and a special call out was made for the need for an ‘actuarial analysis of the lifetime costs’ of vulnerable children.

    The Forecasting Future Outcomes report is a key step in realising these aims.

    The Forecasting Future Outcomes report

    The report was authored by a team from actuarial consulting firm Taylor Fry, of which I was a part. To obtain the results presented in the report, we analysed more than seven million anonymous records of people born in 1990 or later, as well as the records of their parents. This data was supplied by government departments in areas including child protection, justice, education and health.

    The underlying analysis is essentially a valuation model – albeit a bit more complex than your typical one. For example, the model makes forecasts of about 40 different outcomes and services. It covers areas such as interactions with child protection and justice agencies, educational attainment and parental risk factors. In addition, the forecasts are made at the individual level – each person gets their own forecast. And because of the complexity of the interactions in the model, micro-simulation techniques are used to make the projections.

    Startling results

    The headline finding, quoted in several newspaper articles 2,3,4 is that seven per cent of people aged under 25 will account for half of the estimated $100 billion cost of the state’s key social services by the time they are 40 years old. Or, in other words, heavy use of social services is concentrated in a small group.

    In some sectors, this concentration of cost is very pronounced. For example, one per cent of people who are aged under 25 will account for about one-third of the estimated future costs of justice services.

    The analysis also highlighted the importance of early intervention, with one per cent of children aged under five accounting for 45 per cent of the estimated future costs of child protection services for that age group.

    The report also identified six vulnerable groups – including vulnerable children aged five and under, and young people affected by mental illness – to prioritise for future programs. These groups had much higher use of social services and poorer social outcomes compared with the NSW average.

    In all six vulnerable groups, Aboriginal people were over-represented, demonstrating how far there is to go in closing the gap.

    Where to from here?

    To those who work with vulnerable children, many of these findings are unsurprising. They are well aware of the seemingly inevitable trajectory vulnerable people find themselves travelling. But what is new is the analysis confirms what is seen in the field, reliably quantifies those differences and puts a fiscal cost on those differences. In particular, the cross-agency and long-term view provided by the analysis had not been available previously, and this is proving valuable.

    What is generating considerable excitement is the ability to use this analysis to help implement better targeted interventions, which promise to deliver genuine improvements in people’s lives and fiscal savings in the long term.

    Yet in many ways, the analysis presented in the Forecasting Future Outcomes report is the easy bit. Unfortunately, working out what interventions are likely to work remains a ‘wicked problem’.

    It now falls onto policy experts, armed with a better knowledge of who to target and what is at stake, both socially and fiscally, combined with front-line workers and academics, to take that knowledge and generate more effective interventions for vulnerable people. Of course, not all (many?) of the proposed interventions will work as intended. But through continued data analysis, the Government will be provided with feedback on what is working and what is not – and so the things that are working can be expanded and those that are not stopped in a kind of social policy control cycle. At the same time, actuaries will continue to provide that valuable link between experience and policy, articulating the needs of vulnerable people through analysis and evidence.

    As first published by Actuaries Digital, 5 September 2019

    [1] https://www.theirfuturesmatter.nsw.gov.au/__data/assets/pdf_file/0012/668649/Forecasting-Future-Outcomes-Stronger-Communities-Investment-Unit-2018-Insights-Report.pdf
    [2] https://www.smh.com.au/politics/nsw/ground-breaking-report-social-services-overhaul-20190704-p5244n.html
    [3] https://www.smh.com.au/politics/nsw/billions-spent-investing-in-the-wrong-stuff-social-services-sector-responds-to-report-20190705-p524hq.html
    [4] https://www.smh.com.au/national/beyond-the-folbigg-tragedy-silent-mental-illness-in-parents-the-greatest-risk-for-children-20190724-p52a7w.html

  • RADAR 2019

    Welcome to RADAR 2019, Taylor Fry’s inside look at the general insurance industry, the state of the market and what it means for insurers

    Here’s a quick overview of the highlights from RADAR 2019, our class-by-class round up to the end of FY2019:

    • Overall underwriting results for general insurers worsened over the year to FY2019, affected by catastrophic weather events, including Sydney hailstorms in December 2018, and Townsville floods in January and February 2019. The net loss ratio for the industry increased from 62% in FY2018 to 69% in FY2019, causing the net underwriting combined ratio to increase from 87% to 93% over the same period.
    • Improved risk management and sophisticated pricing approaches are assisting insurers to maintain profitability in personal lines. But ongoing impacts from the royal commission have made insurers increasingly conscious of the need to balance shareholder and policyholder considerations. As well, flood exclusions may be challenged if proposed changes to unfair contract terms are adopted, requiring large premium increases for property policyholders in high flood-risk areas.
    • The commercial insurance cycle appears to have turned in 2017, with rates hardening across most commercial classes. Despite this, profitability for many commercial classes continue to be under pressure. Profitability for Commercial Property was affected by catastrophic weather events, while profitability for Professional Indemnity has been impacted by rising litigation and class actions.
    • Overall reserve releases on long-tailed classes were subdued during FY2019, which put further upwards pressure on incurred claims and loss ratios. In particular, Public and Products Liability experienced reserve strengthening during FY2019, which contrasted with several years of reserve releases in the preceding years.
    • Falls in interest rates over FY2019 have resulted in a significant increase in long-tailed claim reserves. This places particular importance on having an investment strategy that has Asset Liability Management (ALM) at its core. Insurers with matched portfolios experienced capital gains in their assets to offset the increases in claims reserves.

    Download RADAR 2019 for our expert insights on the shifts and trends in our industry to help you navigate your way through the ever-changing insurance landscape.

    If you’re not currently subscribed to our updates, and you’d like to receive news from Taylor Fry, subscribe here.

    Find out more about our Appointed Actuary and General Insurance services.

  • Ethical artificial intelligence

    As artificial intelligence becomes cheaper and easier to build and apply, it is natural that more attention has been given to the ethical issues that surround it.

    Some examples are obvious – if a prediction model can be made more accurate (e.g. an insurance premium) using variables such as race, is it ethical to do so? However, there are other types of ethical issues, some subtle, that can arise too.

    One interesting contribution to this topic is the EU’s Ethics Guidelines for Trustworthy Artificial Intelligence, released in April 2019 and put together by a European group of artificial intelligence experts. By expanding to the term ‘trustworthy’ the guidelines also include recognition that artificial intelligence should also be lawful and robust, in addition to ethical.

    The most practical part of the document is a toolkit of things to consider across seven areas that speak to different aspects of artificial intelligence risk.

    1. Human agency and oversight: Including fundamental rights, human agency and human oversight
    2. Technical robustness and safety: Including resilience to attack and security, fall back plan and general safety, accuracy, reliability and reproducibility
    3. Privacy and data governance: Including respect for privacy, quality and integrity of data, and access to data
    4. Transparency: Including traceability, explainability and communication
    5. Diversity, non-discrimination and fairness: Including the avoidance of unfair bias, accessibility and universal design, and stakeholder participation
    6. Societal and environmental wellbeing: Including sustainability and environmental friendliness, social impact, society and democracy
    7. Accountability: Including auditability, minimisation and reporting of negative impact, trade-offs and redress.

    Taken from: Ethics guidelines for trustworthy artificial intelligence 

    For those interested, it’s worth a read, but some thoughts I had on the way through:

    • Human Agency (#1) is a challenge for prediction engines. Many models produce a recommended course of action but won’t always contextualise choice for people making the decision and may lead people to trust a computer more than a human recommendation; in medicine for example, a treatment option often needs significant amounts of context that allow informed decision making. It also reminded me of David Wilheim’s presentation from the 2017 IDSS where car insurance repairer recommendations had to be both useful but promote choice and agency.
    • Resilience to attack (#2) may range from serious hacking attacks (like hacking a model) through to gaming (e.g. a user might fiddle with inputs in an insurance rating engine to find cheap rates attached to unusual configurations). With cutting edge vision recognition systems able to be fooled by stickers, it’s a timely reminder than not all users of a system will do so in good faith.
    • Transparency (#3) is an area that has developed significantly over the past decade. While models have grown more complex, there are a variety of ways to unpack a model, and see why a particular output is being produced for a certain set of inputs.
    • Fairness (#4) is also an important topic, albeit more subjective. The first challenge is even defining it, which was well-covered in this paper by Chris Dolman and Dimitri Semenovich at the recent Actuaries’ Summit.
    • Environmental impacts (#6) are worth considering, as the demand for computer processing time increases with the complexity of some algorithms, or the popularity of the product. For example, the Bitcoin network now requires the same amount of electricity as a small to medium sized country like Ireland, for a payments network that has significantly less throughput than other networks like Visa or Mastercard. Much of this mining is done in China, where about half the power is generated from coal. While not strictly artificial intelligence, it’s easy to believe that the development of currencies like Bitcoin did not have environmental concerns front and centre.

    More generally, it’s easy to see that some high-profile uses of artificial intelligence will have to embrace more formal governance structures along the lines of the EU guidelines; executives, regulators and consumers will all have questions about computer models that need to be answerable, and artificial intelligence-based decisions need to be defendable. This requires a good mix of technical skills, business understanding and concern for the public good; perhaps another opportunity for actuaries?

    As first published by Actuaries Digital, 6 August 2019

  • After shocks

    Extreme weather events show no sign of abating and as New Zealanders attempt to deal with the fallout, nothing it seems is immune from scrutiny – from solvency and premium increases to property values and the cultures embedded in the NZ insurance industry itself. Ross Simmonds reports

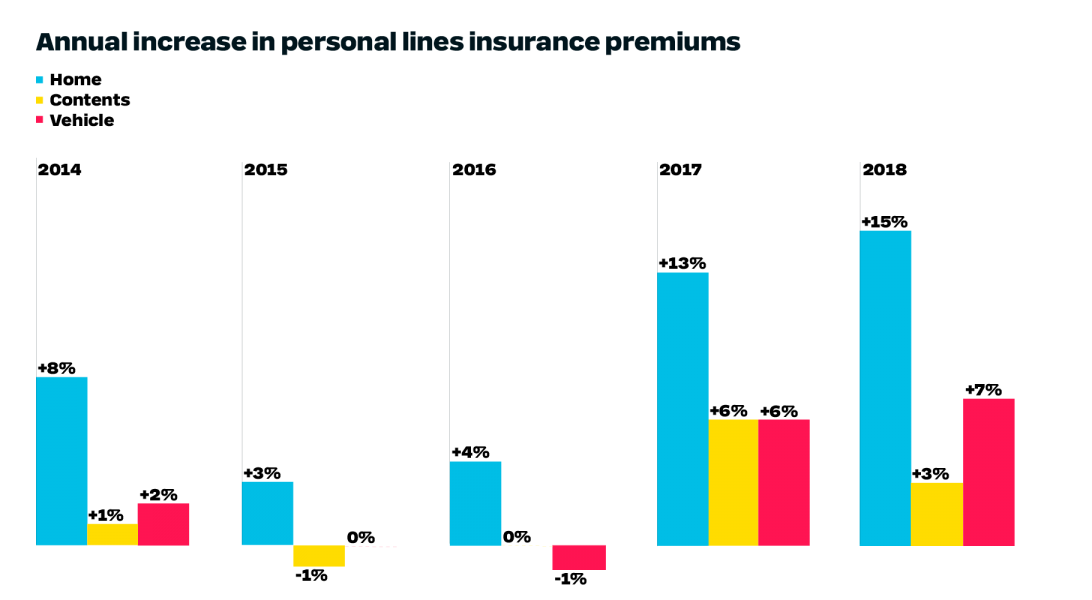
    Last year was another eventful one for the NZ insurance market, with losses from weather-related events again high ($226m in 2018 and $243m in 2017), suggesting more frequent large-loss weather events are here to stay. Insurers have responded to this by raising premiums, which has helped them remain profitable. Consumer Price Inflation data shows that insurance premiums for all personal lines classes of business have increased over the past two years, with double-digit increases in home premiums for both years.

    Source: Statistics New Zealand, table reference CPI013AA

    2018 also saw two insurers, Tower and IAG, increasing the level of risk rating applied to home insurance. The increase in risk-based pricing was initially focused on earthquake risks and resulted in higher premiums for regions such as Wellington, Marlborough, Wairarapa and Hawkes Bay, with reports of premium increases in the thousands of dollars for some risks.

    IAG decision causes concern

    The focus on risk rating early in 2019 was marked by reports that IAG – the largest insurer in NZ, accounting for roughly 44 per cent of the market[1] – was not accepting new home or contents risks in the Wellington region. While IAG has denied this is a blanket policy, it is nonetheless clear the company is looking to limit its exposure to risk in the Wellington region. This decision is driven by the higher solvency requirements for Wellington risks, given the city’s high exposure to earthquake risk. Real estate agents are worried about the impact this may have on the housing market, given banks require homeowners to hold insurance on mortgaged houses.

    While the current issue is focused on Wellington and earthquake risks, this should be ringing warning bells for property owners exposed to other risks such as flood and rising sea levels. Insurers are not obliged to offer cover, especially if they feel the risk is too great, and this will impact property values. Responding to media questions on IAG’s stance in Wellington, Commerce and Consumer Affairs Minister Kris Faafoi noted the government is watching the issue closely, but is still “a long way away from intervention”.[2]

    We expect insurance pricing, and the impact this may have on private market willingness to insure high-risk areas, will remain a topic of contention. This may see government involvement at some stage in the future, especially if affordable cover is not available.

    Regulatory review remains a key item on our radar. Three recent developments are:

    • The review of life insurer conduct and culture undertaken by the Financial Markets Authority (FMA) and the RBNZ
    • The RBNZ noting there has been a reduction in solvency ratios for general insurers over the past year, which indicates a reduction in the capital strength of the sector
    • The liquidation of CBL Insurance following an RBNZ commissioned review.
    Review of life insurer conduct and culture – better customer focus needed

    This review was undertaken in the second half of 2018 and identified a lack of focus on good customer outcomes in the NZ life insurance industry, with some insurers viewing third-party advisers as the customer rather than the policyholder themselves. A key recommendation of the review is the expectation that insurers “remove or substantially revise incentives linked to sales for frontline salespeople …”[3] by 2020.

    While the review has focused on life insurers, it recommends that “all insurance sectors should be actively considering conduct risk within their business. Given the similarities between life and non-life insurance, it is possible that the vulnerabilities identified … may exist across the broader insurance industry. We expect all insurers to assess their conduct and culture governance frameworks, and consider and act on all relevant recommendations …”[4]. This highlights there is likely to be a focus from the regulators on how insurers are:

    • Governing conduct and culture through their boards
    • Overseeing how intermediaries are selling and managing their products
    • Designing and reviewing products to ensure they provide good customer outcomes
    • Training staff on all aspects of the products they sell and support
    • Setting risk management policies to include conduct risk
    • Educating staff on what good conduct and culture is, with a focus on good customer outcomes
    • Recording and resolving customer complaints
    • Reviewing commission structures for intermediaries.
    Reduction in solvency ratios for general insurers – capital requirement rises on the way?

    RBNZ’s May 2019 Financial Stability Report[5] noted there had been a reduction in the solvency ratios across all classes of insurers, with the reduction mainly attributable to larger insurers.

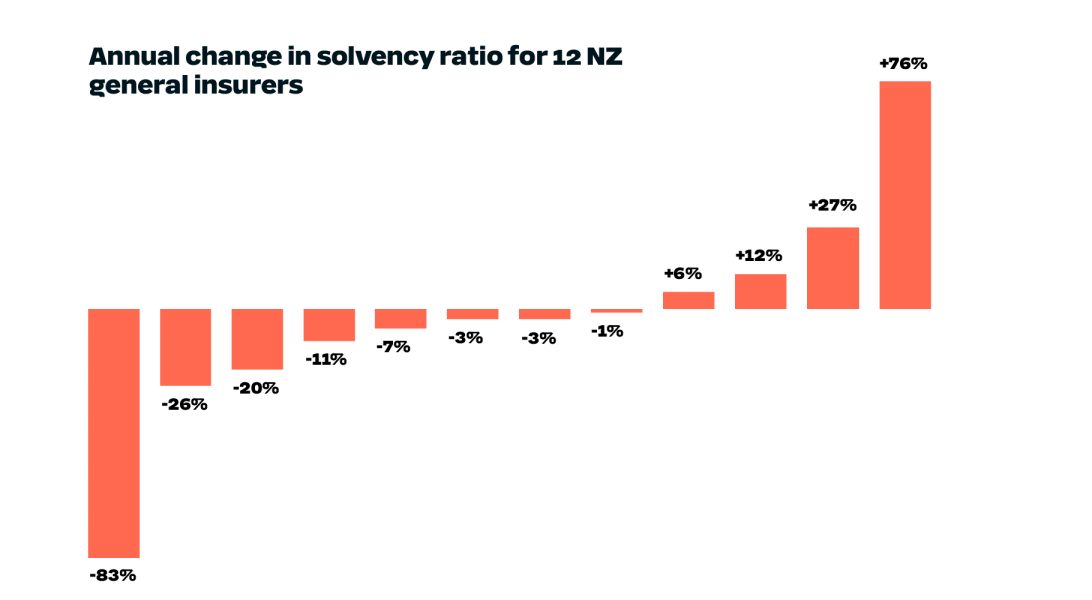
    The following chart shows the annual change in the solvency ratio for the 12 largest general insurers, taken from their latest financial accounts. It covers only those insurers who report solvency under RBNZ solvency standards. Several insurers are exempt from these standards and are instead subject to solvency requirements from their home regulators.

    Source: New Zealand Companies Office

    The chart shows solvency ratios experienced a range of changes over the past financial year among general insurers who report under RBNZ solvency. The four largest reductions in ratios were all predominantly due to reductions in levels of actual solvency capital. Of these, two reductions were due to dividend or capital repayments where companies had consciously reduced their capital levels. The remaining two reductions were due to retained losses (which erodes capital) over the past financial year.

    During 2018, the RBNZ reviewed the Capital Adequacy Framework for banks and is proposing increases in the capital requirements for banks following this review. It is clear RBNZ expects insurers to maintain a prudent level of capital above the minimums set out under their solvency requirements, and they are considering requiring insurers to maintain solvency buffers as part of their forthcoming review of the Insurance (Prudential Supervision) Act 2010. If a solvency buffer was introduced this would effectively require insurers to hold more capital which will likely result in increased costs for consumers.

    Liquidation of CBL Insurance – lessons for the market

    CBL was placed into liquidation in November 2018, although an interim liquidator was first appointed in February 2018. While CBL was regulated by the RBNZ, most of its business was written in overseas markets, predominantly Europe. The main factor that has contributed to the failure of CBL was significant growth in the volume of French builders’ warranty insurance. A key characteristic of this class of business was that it was particularly long tailed, with a 10-year claim notification period. In July 2017, the RBNZ directed CBL to maintain a solvency ratio of 170 per cent, due to concerns about the adequacy of CBL’s reserving. Subsequent increases in the reserve levels resulted in CBL breaching its 170 per cent threshold in late 2017. An independent review of CBL’s reserves commissioned by RBNZ was released in February and resulted in CBL’s solvency levels falling below their minimum levels required under the solvency standards. The first liquidators report in December 2018 found CBL was insolvent at the date of the interim liquidation.

    What does this mean for the NZ general insurance market? RBNZ has commissioned an independent review into its supervision of CBL to identify lessons for itself and the insurance regulatory regime in NZ. This report has just been publicly released and has been viewed as being critical of RBNZ’s handling of CBL, with a key finding being that RBNZ failed to act decisively on concerns they had around CBL’s financial strength. The report also makes recommendations around strengthening solvency standards, which will potentially require insurers to increase levels of capital. There may also be more scrutiny from the regulator on the strength of insurers’ reserving processes, although the report recommends that the RBNZ allocate more resources to their supervisory team, so this may take some time to develop.

    The big issues ahead? Insurance affordability and insurer cultures

    Insurance premiums, particularly for personal lines, have continued to increase and the recent increased focus on risk pricing is likely to see more press on large premium increases. At the same time, insurers are likely to see an increased focus on culture, conduct and financial risk, via solvency levels. We would expect this to result in increased costs for NZ insurers, causing further pressure on premiums. Insurance affordability and availability will remain a big issue for NZ in the next year and beyond.

    [1] https://www.nzherald.co.nz/business/news/article.cfm?c_id=3&objectid=12107489
    [2] https://www.interest.co.nz/insurance/98584/faafoi-tells-insurers-communicate-price-and-policy-changes-more-clearly-wont-force]
    [3] http://www.fma.govt.nz/assets/Reports/_versions/12147/Life-Insurer-Conduct-and-Culture-2019.1.pdf
    [4] http://www.fma.govt.nz/assets/Reports/_versions/12147/Life-Insurer-Conduct-and-Culture-2019.1.pdf
    [5] https://www.rbnz.govt.nz/financial-stability/financial-stability-report/fsr-may-2019

  • Their Futures Matter modelling released

    Earlier today, the NSW Government released Taylor Fry’s report analysing agency data to understand and anticipate the current and future needs of children, young people and families in NSW.

    There are some striking findings in the Their Futures Matter modelling, for example, we predict 7% of the people aged under 25 in NSW will account for half of the estimated $100 billion cost of the state’s social services by the time they are 40 years old.

    In the report, our modelling uses data combining child protection, housing, justice, health, education, mental health, alcohol and other drugs, parental risk factors and Commonwealth government services (welfare, Medicare and PBS).

    Our work will assist the NSW Stronger Communities Investment Unit – Their Futures Matter to design service solutions or enhance existing supports for the benefit of priority groups identified using the modelling. It will also be used in allocating investment to people with the highest needs.

    You can read the full report here.

    More information on the investment approach to thinking about government services, and how it can deliver better outcomes to people can be found here.

  • The surprising life of Taylor Fry co-founder and actuarial guru Greg Taylor

    Entrepreneur, pioneer, academic, musician – Greg Taylor has lived many lives in his 58 years as an actuary and built a towering reputation along the way. Not bad for someone who happened upon the profession looking for an easy life. Elizabeth Finch spoke with the Taylor Fry co-founder and discovered a truly quiet achiever, driven by a desire to do the right thing and an insatiable curiosity for the new.

    You are considered a guru by many in your profession, even by your fellow Taylor Fry co-founder Martin Fry, who said he always felt like a junior partner. How does that make you feel?

    A little uncomfortable. ‘Guru’ is flattering, but unwarranted – I would never recognise it in those terms. With age comes a certain deference, perhaps. I’ve just been around a long time!

    It’s a surprise coming from Martin because I always thought of him as an equal when we were working together, and he’s a lot better at some things than I am. It’s difficult to believe he felt like the junior partner – he may be exaggerating.

    Greg Taylor in our Sydney office

    The Actuaries Institute has awarded you the only gold medal in its 121-year history and speaks of you as a pioneer in your field. How do you explain being the only one?

    I’ve asked myself the same question. In the past, it was unusual to work across industry and academia, which proved a big advantage for me, but it’s an accident I chose that course and others didn’t – a case of right place, right time.

    There’s always a tendency to accord a person superlatives, not only in this but in many aspects of life, to start ranking people. But I don’t see it in terms of rankings – everyone is good at something.

    What do the awards, accolades and international acclaim mean to you?

    Acceptance and recognition of my peers – that’s important to me – although my interest in research isn’t changed by awards or lack of them. Research is supposed to be useful, so awards also recognise someone thinks your research is useful and the people you mingle with in a research community regard the work as valuable. I can’t ask more than that.

    Despite all the achievements, you remain quite unaffected. Was creating a relaxed culture important in setting up your own business?

    Yes, it was very deliberate at Taylor Fry to have an environment that allowed people to be themselves. Many of the firm’s qualities reflect our early-day reactions against aspects of our previous work lives we thought were unfortunate – or not even quite proper.

    There are some workplaces where rewards come to the noisiest, those who intimidate others and promote themselves. We didn’t think this was healthy and did what we could to prevent it.

    Given that you’re held in such high esteem, have you ever felt pressure to be a role model?

    No, I’ve always just tried to be myself. I actually never aspired to start a consulting firm. That path wasn’t a natural fit for me. I’d never contemplated it or thought it was something I’d be good at. It fractures your life and brings with it the risk of failure.

    Alan [Greenfield, the youngest of the three Taylor Fry co-founders] was the galvanizing force for me. He was the one who said, “Look, we can do this.” It was only then I began to take the prospect seriously. I also took the risk very seriously. Martin did as well. Alan was a bit more gung-ho.

    We were all refugees in a sense, driven by what we saw as the enormous shortcomings of our then employers. It was so bad and we doubted moving elsewhere would improve the situation.

    Did the risk weigh heavily on you at the time?

    Risk is something you ignore at your peril, even if you rate the risk as low, which I didn’t. It’s wise to be constantly aware of it, to never overlook it. Not that it was ever likely to be forgotten. Martin and I had just mortgaged our houses and our wives regularly reminded us of this. That said, over the years, my wife Rhonda provided a great deal more support than was my due.

    Easy rider: Greg Taylor enjoys some time out from actuarial pursuits on a farm in NSW, 1977

    Going right back to your beginnings, how did you decide the actuarial profession was for you?

    It’s a shameful story! I grew up in Adelaide and performed reasonably well at school but always regarded study as an unfortunate nuisance. I made a very poor decision in my final year of high school, abandoning science subjects to gain some soft options for myself – very silly – though I persevered with maths because it involved no effort. I was just looking for an easy life.

    My family lived modestly and my parents had suggested engineering to help me rise out of the mire. We’d never heard of actuaries, hardly anyone in Adelaide had. But after a door-to-door insurance agent regaled my father with tales of these people who earned vast sums, I thought that sounded pretty good.

    I figured the course would be fairly simple for me to knock off. Foolish! A decision without foundation or wisdom, and it meant no university. Instead, at age 16, I began actuarial study – a correspondence course in those days – and took a job at MLC Assurance Company in Adelaide.

    How did your parents respond at the time to the path you chose?

    My mother was always extremely proud. My father was a product of his era – enigmatic, a man of few words, so I was never entirely sure how he felt.

    What kind of person was your father – what did he do?

    His qualifications were never clear to me. That generation of people had very chequered careers because they came through the depression, then the war. He seemed to be a semi-qualified accountant. He then became a newsagent and later bought a clothing business, which he managed for many years. He was an entrepreneur, no doubt.

    He went to war in New Guinea, but never talked about it. When I was eight or 10, war was glorious to me. I was born in the very last months of the war, in 1945, and I couldn’t get enough of it. But when I asked him about it, saying, ‘Why can’t we go to Anzac Day and march? Why don’t you go down to the pub with all the guys?” He just said to me, “The people who want to talk about it weren’t there.”

    It affected him and many others very deeply. They were very brutalised.

    It’s perhaps apt you’re known for treating people in a very human way. How did your ethical passion come together in business with your mathematical passion?

    It consists of two components. The first is to do the right thing, and that involves being honest and telling people exactly what you think. The second is if you tell them what you think when it’s uncomfortable for them, then they know they can rely on you for an honest opinion.

    It’s easy to say things a client wants to hear and it’s hard to say things they don’t want to hear – but the reward for that is trust. This was top of mind when we began Taylor Fry. You know the old saying, ‘what’s my opinion on this? What opinion would you like?’ We were very careful to avoid falling into a ‘yes men’ mould like that, and I always found honesty generally profitable.

    Occasionally, it has the opposite effect, when a client can’t afford to hear honest advice, even if they respect it, simply because it blows their business plan apart. Consequently, my rule of thumb was I’d be fired roughly once every 10 years!

    How did that affect you when it happened?

    It’s not pleasant. It’s easy enough to say all this now but, at the time, there’s a great deal of self-doubt. You think, I’ve given my advice and I’ve stood by it, but am I being obstinate? Could I have done something else?

    It’s one thing as a consultant to be fired by a client – it’s not great, but you can move on. It’s quite another thing as a corporate employee to be fired or, more likely, to be sidelined – constructive dismissal, it’s called. That’s a lot more serious from a personal viewpoint.

    Not only is there self-doubt but paranoia can easily set in. What else will they do? Maybe they want to discredit me, damage my reputation. It’s extremely unpleasant, but there’s nothing you can do. As with any journey, you can only keep putting one foot in front of the other. Eventually, everything comes right or everything goes wrong. Fortunately, it hasn’t all gone wrong for me.

    Partners in time: Greg Taylor at home in 1990 with wife Rhonda

    One of your career highlights is setting up Taylor Fry. How much of an impact did it have on you?

    I’m generally very bad at entrepreneurial activity, it’s not at all natural for me, so it had a considerable personal impact. I had to try to think as a leader, rather than a follower who sits in a corner working away quietly. I needed to change my perspective in everything I did, to consider how the company’s ability to gain and maintain business would be affected.

    Luckily, there was a certain acceptance of the more bookish personality in the industry then. Some clients even seemed to regard it as an advantage.

    When you look back at your time there, what place do Martin and Alan have in those reflections?

    In Martin’s case, he was such an effective head in our Melbourne office, we always knew it wouldn’t require our mental energy. And he’s a good friend. It’s certainly a bonding experience jointly mortgaging your houses.

    It’s a very different relationship with Alan – we go back a long way. Of course, I’m much older, although the gap’s narrowing now! He was a university graduate, about 21 or 22, when we first met, and I hired him for his first consulting job. This was at PwC (Coopers and Lybrand back then) and he was gung-ho from the start – a good thing because I’m not at all like that. Alan has always been a good counterbalance to my personality. It was bonding because we were a group of only five or six in those early C&L days.

    There have been a few experiences with Alan. Once, when he was working in the US and still assisting me with research in Australia, we devised a ruse to create a research meeting in New Orleans. When we arrived, the city’s famous jazz festival was on, which we hadn’t anticipated. Consequently, our ‘meeting’ started at midday and ended at 6am.

    What was the impetus to leave Taylor Fry after 15 years and was it difficult to return to academic life after many years running your own business?

    It wasn’t difficult at all – I’ve always had one foot in each camp. I also grew up at a time when 65 was the conventional retirement age, so it was a landmark age for me. Once I decided, I looked forward, not back and as the date approached, I realised there were other things I’d like to be doing.

    For example, I had musical interests before, playing guitar. As a child, I spent a great deal of time with a neighbourhood friend whose family was musical. It was very inspiring. I was about 10 when I resolved to play the guitar – despite my mother dismissing it as a ‘cowboy’ instrument.

    After we established the company, I tried to continue, but the demands of a new organisation were all consuming, and half-measures were unsatisfying. It was a sacrifice to pack away the instrument, a wrenching experience. I had spent the previous 14 years working hard at being a guitarist developing jazz skills, so this was a big factor in considering new possibilities when I left Taylor Fry.

    Nowadays, I still prefer jazz, and challenge myself with rock, blues and country. It’s a solitary pursuit, with the very occasional public exception. And no singing, just the music.

    And all that jazz: Greg Taylor’s passion for playing guitar began at age 10

    On top of your musical accomplishments, you have also completed two PhDs – what compelled you?

    The wrong decisions of my youth began to haunt me. I was shamed by my lack of qualifications in areas I enjoyed but abandoned. As an actuarial student, I didn’t even have an undergraduate degree, and I was terribly frustrated by the pragmatism and inelegance of actuarial theory. At that point, I wasn’t sure I wanted to be a practising actuary.

    I’d had my eye on a brand-new actuarial course at Macquarie University and, in 1969, joined the faculty, teaching and researching.

    During all of this, the Vietnam war had become a factor. Australia was involved in the war in a big way by then. It was a highly political subject – more horrible than we knew. I had been drafted for national service and deferred twice already because of my studies. The third time, in 1971, my application for exemption was denied.

    When I was called to attend a medical examination, a football injury I’d recently sustained prevented me from enlisting. At first, the examining doctor didn’t believe I couldn’t straighten my arm, but he eventually accepted the truth and that was the end of that. I extended my research into an actuarial mathematics PhD over the next three years and it was more or less an armchair ride.

    The science PhD came at an incredibly exciting period of discovery in theoretical physics – in fact, the last major advance in that field was in 1984. There were fundamental advancements in the Sixties and Seventies and I wanted to be part of it.

    Greg Taylor receiving the Actuaries Institute Taylor Fry Silver Prize

    With your passion for research, you could easily have remained exclusively in academia, yet you chose to traverse the academic and commercial worlds throughout your working life. Why?

    An experience in the UK was pivotal. In 1975, my sabbatical year, overseas travel was very rare, but I was keen to explore and spent my time in England, Scotland and Switzerland. I had written a nice letter to the UK government actuaries department and was offered a job in a small unit at the department of trade, formulating new ways of assessing insurance companies following a large UK insurance failure in the Sixties.

    The unit was headed by Bobby Beard*, a very, very famous actuary at the time. To work with him, well, you just couldn’t say no. He was the guru of the time.

    I went along thinking he was like a god and I wouldn’t get to talk to him, but he always listened to me and was interested in my ideas. I couldn’t believe it. And he was a very nice guy. In my experience, the people at the very top of their professions have been the most approachable.

    That year, and Bobby in particular, influenced me enormously in pursuing a consulting career. It confirmed my own thought that an actuarial fellowship would equip me to explore much more than academia.

    *In 2008, Greg was awarded the Finlaison Medal by the UK’s Institute and Faculty of Actuaries, a nostalgic salute to his revered mentor Bobby Beard, who had also received the accolade, 36 years earlier in 1972, then known as the Silver Medal.

    Over time, claims reserving became your specialty – what sparked your interest?

    I fell into it at first. When general insurance began to acquire actuaries, they rarely did anything other than claims reserving, so that’s where I started.

    Then, within the first six months of my consulting career, I became involved in legal proceedings that focused on loss reserving – and my interest was sharpened. The argument back and forth and objections raised about my methodology motivated me to innovate and improve it. When the legal proceedings ended after three years, I couldn’t pack it up and never think about it again.

    What do you see as your most meaningful contribution to the actuarial profession?

    I’ve never thought of it on any grand scale. It’s a collection of small things. I would like to think my endeavor to promote more analytical approaches to loss reserving has rubbed off in some way. You can shift people’s thinking marginally, and influence them to think that maybe we shouldn’t just look at a bunch of numbers and make an informed guess, that we should use more formal analysis sometimes. That’s the contribution I’d like to make.

    What is the biggest lesson you’ve learned?

    That pursuing the qualities of integrity and honesty doesn’t necessarily have great drawbacks. For me, there has been no real punishment. I was fired every 10 years, but that’s not much, you know.

    In retrospect, it also seems significant that we aspired to create a culture at Taylor Fry where people are happy and feel valued. We just thought It was a good way to do things. It was more important to us than making huge amounts of money.

    You seem to inspire so many people. Who or what inspires you?

    I’m always inspired by the people whose thought processes I can see are reaching beyond mine – when I think, I wish I could have done or said that.

    What are your hopes for your future – professionally and personally?

    There’s always more to achieve! I’ll continue researching – I’m always looking for new things. It’s easy not to venture outside your area of authority, but to me that’s stagnation. Ultimately, you enter your dotage and lose relevance, but there’s more to be done in the meantime.

    Music is a much more difficult area. I’m confronted daily with my inadequacies, but I don’t think I’m losing dexterity yet. There’s no shortage of challenges, so I’ll continue to enjoy it while I can. I do recognise there’ll come a time when it isn’t possible, but that can wait until the day it happens – I don’t look too far ahead. I remind myself every day how lucky I am.

    Enjoy this read? Take a look at our piece on Taylor Fry co-founder Martin Fry

    Want to know more about the history of Taylor Fry? Check out our About page