Category: Uncategorized

  • RADAR FY2025 – Balance and meaningful action vital amid huge wins

    RADAR FY2025 – Balance and meaningful action vital amid huge wins

    What are the big themes for insurers following another year of record-breaking profits? In RADAR FY2025, Taylor Fry offers key insights on how to navigate the shifting landscape, with its greater focus on transparency and customer experience, increasing AI adoption and the ever-present risks of an evolving climate.

    The general insurance industry has again posted its strongest result in more than 10 years with a profit after tax of $7.3 billion over the 12 months to 30 June 2025, according to recent data from the Australian Prudential Regulatory Authority (APRA).

    While we expect the escalating figures will intensify focus on pricing practices and fairness, we stress the importance of perspective through a long-term view in our latest class-by-class analysis of the sector, RADAR FY2025.
    Dive into RADAR FY2025 for a raft of expert analysis, reader-friendly charts and insightful videos covering the major happenings, emerging trends and impacts for insurers.

    Here’s an overview of some of the key themes you’ll find at our RADAR FY2025 hub …

    Volatility vs the long-term view

    “Understandably, consumers may question the big result in a time of ongoing cost-of-living and insurance affordability pressures,” principal Scott Duncan says. “But insurance is naturally a volatile business year on year and it’s critical not to view profits solely from a one-year window. Insurers were hit particularly hard during COVID.”

    This experience is reflected in the share price of the larger insurers. “The share price for Suncorp, IAG and QBE have increased at twice the rate of the broader market since 2020. Yet when we take a longer-term view, over the past 10 years, we see their share price has matched the broader market.”

    Scott says this short-term volatility but steadier, long-term picture demonstrates the core role of insurance. “Insurance acts as a shock absorber for households and the broader economy to ensure the sector can restore community when times are bad.”

    Opportunities for the taking

    A run of positive experience over the past two years, however, provides the industry with vital opportunities to reflect and invest purposefully in better serving customers. “Previously, insurers reported years of muted returns through extreme weather events and COVID-19, with sustained losses in the householders class,” he says. “Supported by robust bottom lines, investing in customer relationships now will be the defining strategy to secure long-term trust and loyalty.”
    “Investing in customer relationships now will [lead to] to long-term trust and loyalty.”

    The response to Cyclone Alfred, Scott says, is a good example of a customer-first approach. “Insurers provided specialist response teams, which resulted in faster claims handling and improved communication with customers.”

    The industry is also investing heavily in AI to improve underwriting and claims processes. “We’re seeing claims assistants summarising product disclosure statements and recommending next best steps for claims managers,” Scott says. “On the underwriting side, AI is being used to obtain relevant information, reducing the information collected from customers.”

    What’s driving the big result

    Looking at the figures, RADAR FY2025 shows direct insurers recorded a $6.7 billion profit after tax, the highest on record, driven by several factors, including catastrophic losses coming in below expectations, several years of double-digit premium increases, strong investment returns and reserve releases.

    Insurers will need to place the customer at the centre of proactive initiatives … to help foster policyholder loyalty and confidence in their insurer to do the right thing when it counts the most.

    Scott draws out householders, domestic motor and a softening market as key highlights across the underwriting result. “While householders recorded an insurance service result of $1.16 billion – the strongest in more than 10 years – APRA data shows a continued decline in risks written over 2025, with evidence that consumers who retain insurance are increasing excesses to offset cost-of-living pressures,” he says.

    Signs of a softening market

    With strong signs of a softening market, balancing growth and profitability objectives in the near term will be challenging. “Insurers will need to place the customer at the centre of proactive initiatives, such as focusing on a seamless acquisition journey or ensuring people are not left with inadequate cover.

    “These types of moves will help to foster policyholder loyalty and confidence in their insurer to do the right thing when it counts the most.”

    For reinsurers, who recorded a $0.6 billion profit after tax – the second highest in the past 10 years – the market is also softening, Scott says. “The pricing and risk selection discipline shown over the past few years will come under challenge.”

    Climate and extreme weather

    With access, affordability and transparency in the spotlight, climate issues, as ever, are adding extra pressure. Scott says, “The recently released National Climate Risk Assessment confirms Australians will continue to experience climate hazards with widespread, cascading and compounding impacts that will reshape risk and influence insurer profitability.”
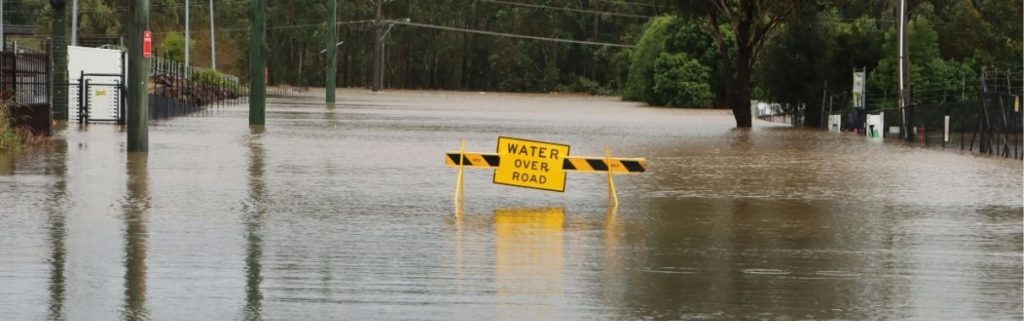
    The National Climate Risk Assessment confirms climate hazards will reshape risk and insurer profits

    Additionally, new technologies and business practices relating to the energy transition will further redefine risk and profitability. “Australia has set records in 2025 in terms of battery storage growth, electric vehicle sales and installed solar power capacity, presenting relatively new risks to the industry.” More risks will emerge as the energy transition progresses, Scott adds, which increases the importance of underwriting decisions and portfolio risk monitoring across many classes of business.

    Eye on the future

    Scott believes pricing transparency will be high on the agenda ahead, as demonstrated by ASIC’s recent focus on how insurers communicate year-on-year changes in premiums to their customers. “Insurers can take action now to improve fairness and transparency, such as giving home insurance policyholders premium reductions for actions they take to improve a property’s resilience.”

    AI adoption at pace will continue for some time, as insurers aim for quicker and more consistent outcomes for customers. “The focus is now switching to AI governance, data security and cyber risk management,” he says. “The more agile insurers will not only protect customers with appropriate guardrails but ensure fair treatment. Empathy and critical thinking are crucial here, especially for the most vulnerable customers.

    “Taking time now to reflect on how to elevate customers’ experience, truly understand their needs and take proactive steps to build more trust will be critical in securing a strong foundation for the future.”

    For more details, or to arrange an interview with Scott Duncan, please contact:

    Elizabeth Finch | +61 473 848 888
  • NSW Ministry of Health releases Taylor Fry report

    NSW Ministry of Health releases Taylor Fry report

    We evaluated a suite of NSW Government suicide* prevention initiatives, which form part of the state’s $2.9 billion investment in mental health services. By linking state and Commonwealth data, our evaluation offers a rare, system-wide view of suicide prevention efforts in NSW – revealing positive impacts as well as opportunities to improve health responses and community resilience.

    The NSW Ministry of Health recently published our evaluation of six programs under the state’s Towards Zero Suicides initiatives – a multi-year effort to reduce suicide and its devastating impact on individuals, families and communities.

    Led by Taylor Fry’s Hugh Miller, Ramona Meyricke and Dennis Lam in collaboration with ARTD Consultants, the evaluation brings together a diverse mix of evidence – including linked administrative data, interviews with stakeholders and consumers, surveys and program-level data – to understand how the initiatives are operating and where they can be strengthened.

    The six initiatives span the full spectrum of suicide prevention supports:

    • Safe Havens
    • Suicide Prevention Outreach Teams
    • Zero Suicides in Care
    • Community Gatekeeper Training
    • Post Suicide Support
    • am/ Youth Aftercare.
    The initiatives reach those who weren’t accessing support or who otherwise wouldn’t have reached out

    Initiatives critical in connecting people

    Our evaluation found the initiatives are reaching thousands of people across NSW – including those who may not otherwise have sought support. In some districts, more than 40 per cent of Safe Haven visitors reported they would not have sought help had the service not been available. This highlights the critical role these initiatives play in connecting with people who may fall through the gaps in traditional care pathways.

    Linked data key in understanding patterns of service use

    A key strength of the evaluation was the use of linked administrative data across NSW Health and Commonwealth systems – including emergency, inpatient, mental health, MBS and PBS records. This enabled a more complete view of service pathways before and after engagement with the initiatives, and broader patterns of service use prior to self-harm or suicide. For example, the evaluation found only one-third of people who died by suicide had a recorded interaction with NSW Health mental health services in the year prior to their death. These insights are helping to build a clearer picture of where the system is working well – and where there are opportunities to strengthen access, coordination and follow-up care.

    Positive outcomes and service gaps

    In terms of outcomes, consumers reported high satisfaction and reduced distress, particularly those accessing Safe Havens, Youth Aftercare and Post Suicide Support. In some districts, Safe Havens were also associated with fewer emergency department presentations for suicidal ideation. At the same time, the evaluation identified important service gaps – and opportunities to improve data capture, referral pathways and access for priority groups, including older people, men and LGBTQIA+ communities.

    For more details, read the overarching report Evaluation of Suicide Prevention Initiatives, or the brief  Summary Report.

    *The pain and loss of suicide for those who take their lives and the loved ones they leave behind affect thousands of people each year in Australia. If this article raises concerns for you, please contact Beyond Blue on 1300 22 4626, Lifeline on 13 11 14 or seek help from these crisis helplines and support services.

  • When the heat is on: Where Australia’s workers face greatest risk

    As temperatures rise and heatwaves become more frequent, workplaces need to determine the risk of heat for their workers. Taylor Fry has developed the Heat-Related Workforce Injury Risk Index to provide a nationally consistent, region-level view of where extreme heat is most likely to translate into workplace injury risk across Australia. We reveal early results including which regions pose the highest risk and why.

    In Australia, roughly 3,000 workers become ill or are injured at work every year due to heat, and that’s likely a significant undercount.

    Australia has warmed every decade since the 1950s with extreme heat events becoming more frequent and intense. These conditions are projected to increase the incidence of heat-related illness and injury in occupational settings.

    At the same time, heat is rising on the labour and workplace safety agenda around the world. Unions and health bodies are calling for stronger, clearer protections for workers against extreme heat. Regulators are reinforcing employer obligations to manage heat risk under existing WHS frameworks.

    The direction of travel is clear: heat is a growing workplace hazard in Australia. For workers’ compensation schemes, self-insurers and regulators, this raises important questions:

    • Where is heat most likely to drive increased claim frequency?
    • Which regions and industries face structurally higher exposure?
    • How might rising temperatures affect scheme sustainability over time?
    • Where should prevention efforts be prioritised?

    To help answer these questions, we developed the Heat-Related Workforce Injury Risk Index.

    The index is a nationally consistent, region-level tool that maps where climatic heat stress and workforce exposure intersect to create elevated injury risk.

    The index brings together three components:

    1. Hazard – How often local conditions exceed safe working heat thresholds

    We measure heat stress using Wet Bulb Globe Temperature (WBGT), the internationally recognised standard for occupational heat stress used by occupational health and safety experts globally. WBGT combines air temperature and humidity (as well as wind speed and solar radiation) to reflect how effectively the human body can cool itself through sweating. This is incorporated using BoM daily weather data.

    2. Exposure – How many people are working in heat-exposed industries in that region

    This is measured using “place of work” data, allowing us to map the daytime distribution of workers across industries and regions.

    3. Vulnerability – The baseline injury risk profile of workers in each industry

    Vulnerability reflects differences in underlying injury rates across industries, using national workers’ compensation data. 

    Who is feeling the heat?

    Heat risk is not evenly distributed across Australia.

    While most SA2 (Statistical Area Level 2) regions record low to moderate index values, a small number stand out dramatically – several  regions record values more than 40x higher than the national median. These are areas where three factors converge:

    • Prolonged periods of high WBGT are common
    • Large concentrations of workers are employed in physically demanding or heat-exposed roles
    • Baseline injury rates are already elevated.

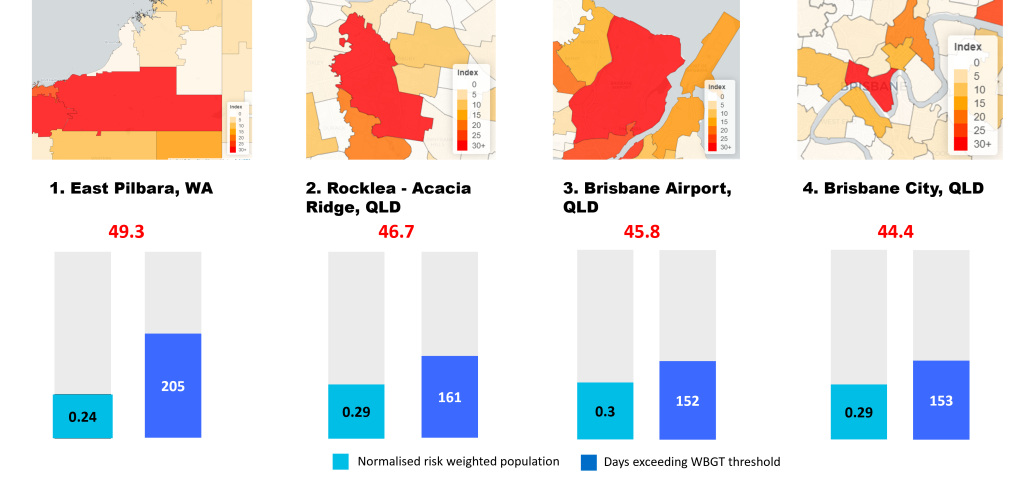
    The highest-risk region is East Pilbara in Western Australia. This region records around 200 days a year above the WBGT threshold, according to BoM data, and supports one of Australia’s largest mining workforces. Many workers are on a fly-in fly-out basis and may arrive from cooler climates, meaning they are often not fully acclimatised to local conditions, which heightens physiological strain.

    Importantly, heat risk is not confined to remote regions that are traditionally associated with extreme temperatures. Industrial precincts on the edges of major cities also feature prominently.

    For example, Rocklea–Acacia Ridge located within Brisbane’s industrial corridor has a dense concentration of transport, warehousing, logistics and manufacturing operations. High humidity, which is a critical driver of WBGT, combined with a large high-risk workforce materially increases exposure.

    Other very high risk areas include:

    • Brisbane Airport: Airport operations involve extensive outdoor or semi-outdoor activity on metal surfaces and large paved areas that radiate heat. Physical tasks such as baggage handling, ground operations and maintenance become significantly more demanding on high-WBGT days. In addition, workers are often required to wear high-visibility and specialised PPE, such as anti-static garments used around aviation fuels and oils, which are not always conducive to ventilation and cooling.
    • Brisbane City: Even in a metropolitan CBD environment, workforce density and climate exposure can combine to produce elevated risk. Heat risk is not only about remote mine sites. It is also about how many people are working, what they are doing, and how often conditions exceed safe thresholds.
    Top four SA2 regions with the highest Heat-Related Workforce Injury Risk Index

    These results show heat risk extends beyond specific sectors, regions, or occupational groups traditionally associated with extreme temperatures. Developing a more nuanced and granular understanding of who, where, and when workers are at risk will be increasingly critical as Australia’s climate continues to warm.

    How can the index be used?

    The Heat-Related Workforce Injury Risk Index is designed as a practical decision-support tool.

    Organisation typeHow the index can help
    Workers’ compensation schemes
  • Identify regions and employer groups where claim frequency may be sensitive to rising temperatures
  • Support analytical insights into emerging heat risk drivers and sustainability analysis
  • Enable informed discussions with employers and industry groups on heat-related risk.
  • Safe Work regulators
    and policymakers
  • A geographically granular view of occupational heat risk
  • Evidence to inform prevention campaigns and industry guidance
  • A data-driven foundation for understanding how climate change may reshape workplace injury risk profiles over time.
  • Self-insurers and
    large employers
  • Highlight sites and regions requiring enhanced heat management protocols
  • Assist with prioritisation of investments in heat risk reduction measures such as improved shade structures, ventilation upgrades, hydration programs, or shift redesign
  • Support targeted adoption of emerging heat management technologies, including wearable heat-strain monitoring devices or phase-change cooling vests.
  • The index supports targeted, proportionate action, directing attention and investment to when, where and who heat risk is most materially concentrated.

    Looking ahead

    As temperatures rise, areas considered low risk today may face greater heat exposure in the future. Changing workforce patterns — as industrial hubs grow, shift, or relocate — will further shape how and where workers experience heat stress. Understanding the evolving interaction between climate and occupational exposure will be key to managing future workforce risk.

    We’re continuing to refine and extend the Heat Risk Index to improve the evidence base. We welcome collaboration with schemes and employers interested in applying these insights.

    To learn what heat risk means for your organisation or portfolio, please connect with our team.

  • Press release – Taylor Fry announces Canberra chief for government practice

    Taylor Fry is strengthening its commitment to public sector innovation with the appointment of actuary and analytics specialist Jeremy Smith-Roberts as principal and Canberra lead.

    Jeremy’s appointment marks the launch of Taylor Fry’s new local presence in the nation’s capital, providing on-the-ground support to its government clientele.

    With more than 10 years in government advisory, spanning strategic and operational analytics across welfare, health and disability, national security and Defence, Jeremy will spearhead client engagement in the region. His experience in workforce planning, including the gender pay gap and career pathways, will also assist in broadening Taylor Fry’s offering.

    Taylor Fry principal and Sydney-based government lead Dr Hugh Miller says, “Government increasingly seeks to base policy on data and evidence, and our quantitative skillset means we’re well positioned to support this. Jeremy has an exceptional track record of adding that value to government so is a welcome addition to the team.”

    Jeremy believes the complexity of government projects requires highly specialised expertise. He says, “It’s critical to have specialist senior staff driving projects, designing solutions and managing that complexity.

    “I’m looking forward to continuing to lead applied analytics projects for government. Taylor Fry is known for exceptional commitment to quality data analytics products, services and advice. I’m excited to build on the team of incredibly capable actuaries by growing a Canberra-based presence. We’re focused on supporting the Commonwealth and ACT governments with pragmatic and robust evidence-based advice, and solutions that deliver results.”

    Hugh says the new location will yield benefits for Taylor Fry and its government network. “Having a physical Canberra presence will be great for our clients and reflects our growing practice across domains like disability, education, employment and health.

    “We also expect the move to Taylor Fry will provide new opportunities for interesting work for Jeremy and the team.”

    View Jeremy’s full biography.

    For more information, please contact:

    Elizabeth Finch, Communications Manager, Taylor Fry

    Elizabeth.Finch@taylorfry.com.au, +61 2 9249 2900

  • NSW Ministry of Health releases Taylor Fry report

    We evaluated a suite of NSW Government suicide* prevention initiatives, which form part of the state’s $2.9 billion investment in mental health services. By linking state and Commonwealth data, our evaluation offers a rare, system-wide view of suicide prevention efforts in NSW – revealing positive impacts as well as opportunities to improve health responses and community resilience.

    The NSW Ministry of Health recently published our evaluation of six programs under the state’s Towards Zero Suicides initiatives – a multi-year effort to reduce suicide and its devastating impact on individuals, families and communities.

    Led by Taylor Fry’s Hugh Miller, Ramona Meyricke and Dennis Lam in collaboration with ARTD Consultants, the evaluation brings together a diverse mix of evidence – including linked administrative data, interviews with stakeholders and consumers, surveys and program-level data – to understand how the initiatives are operating and where they can be strengthened.

    The six initiatives span the full spectrum of suicide prevention supports:

    • Safe Havens
    • Suicide Prevention Outreach Teams
    • Zero Suicides in Care
    • Community Gatekeeper Training
    • Post Suicide Support
    • am/ Youth Aftercare.
    The initiatives reach those who weren’t accessing support or who otherwise wouldn’t have reached out

    Initiatives critical in connecting people

    Our evaluation found the initiatives are reaching thousands of people across NSW – including those who may not otherwise have sought support. In some districts, more than 40 per cent of Safe Haven visitors reported they would not have sought help had the service not been available. This highlights the critical role these initiatives play in connecting with people who may fall through the gaps in traditional care pathways.

    Linked data key in understanding patterns of service use

    A key strength of the evaluation was the use of linked administrative data across NSW Health and Commonwealth systems – including emergency, inpatient, mental health, MBS and PBS records. This enabled a more complete view of service pathways before and after engagement with the initiatives, and broader patterns of service use prior to self-harm or suicide. For example, the evaluation found only one-third of people who died by suicide had a recorded interaction with NSW Health mental health services in the year prior to their death. These insights are helping to build a clearer picture of where the system is working well – and where there are opportunities to strengthen access, coordination and follow-up care.

    Positive outcomes and service gaps

    In terms of outcomes, consumers reported high satisfaction and reduced distress, particularly those accessing Safe Havens, Youth Aftercare and Post Suicide Support. In some districts, Safe Havens were also associated with fewer emergency department presentations for suicidal ideation. At the same time, the evaluation identified important service gaps – and opportunities to improve data capture, referral pathways and access for priority groups, including older people, men and LGBTQIA+ communities.

    For more details, read the overarching report Evaluation of Suicide Prevention Initiatives, or the brief  Summary Report.

    *The pain and loss of suicide for those who take their lives and the loved ones they leave behind affect thousands of people each year in Australia. If this article raises concerns for you, please contact Beyond Blue on 1300 22 4626, Lifeline on 13 11 14 or seek help from these crisis helplines and support services.

  • Taylor Fry boosts climate expertise

    As insurers and governments grapple with increasing extreme weather events and the transition to a low-carbon economy, we’re focusing on how actuaries can contribute meaningfully to solutions, with the appointment of climate and financial risk specialist Dr Ramona Meyricke as head of our climate practice.

    Dr Meyricke is the chair of the Actuaries Institute Climate & Sustainability Practice Committee and holds a PhD from Cambridge on the connection between the resilience of supply chains and investment returns in today’s interconnected world.

    She brings more than 20 years’ experience in the financial sector, most recently as Director of Policy and Research at IFM Investors, where she led thought leadership, policy advocacy and strategic initiatives, including on climate change.

    Dr Meyricke says actuaries are well suited to assessing and managing risk in the climate space

    “It has never been more important to understand and manage climate risk and to build resilience – especially in Australia,” she says. “Events like the LA fires and Australia’s east coast floods in 2022 are destroying homes and businesses – they’re challenging communities and pushing up insurance costs.”

    As the impacts of climate change worsen, Dr Meyricke adds, efforts to reduce greenhouse gas emissions are falling short of what’s needed.

    It has never been more important to understand and manage climate risk and to build resilience – especially in Australia.

    For meaningful progress to take place, she believes we must transition the way we go about business and economic activity. “We must build resilience in our society and communities, as well as our businesses and environment.”

    She says the actuarial skillset is key. “Actuaries are used to assessing and managing risks to our community that are uncertain, potentially catastrophic and often long term – a perfect combination for us to make an impact in the climate space.”

    Taylor Fry co-founder and fellow principal Alan Greenfield says the addition of Dr Meyricke to the team is very exciting. “Ramona was responsible for establishing our climate practice a few years ago, so it’s fantastic to welcome her back as we expand our offering. It’s such a crucial time – for organisations, as they prepare for mandatory disclosures, and for governments, as they ramp up their actions to support achieving net zero.”

    He says Dr Meyricke’s experience and collaborative approach will add critical perspective to the challenges ahead. “Ramona’s ability to draw teams together across sectors, combined with her specialist expertise in climate and financial risk, will help organisations identify, measure and manage climate risk, and capture opportunities arising from the economic transition.”

    Find out more about Dr Meyricke’s work and our how we help our clients navigate their climate risks.

  • LA wildfires – implications for the upcoming Australian reinsurance renewals

    The January fires in Los Angeles are expected to cause tens of billions of dollars in insured losses, with the global reinsurance market integral in covering those losses. What flow-on effects, if any, will this have in Australia? We interviewed a panel of local reinsurers and brokers to find out …

    The sheer size of the event is adding to concerns of its effects reverberating around the world

    In 2024, the Asia Pacific reinsurance market showed the first signs of premium softening, following large rate increases in 2022 and 2023. In the same month as the devastating Californian fires, January policy renewals continued easing with increased capacity and rate reductions across the global market (see chart below, with data sourced from Guy Carpenter, presented by Artemis.bm). But will this experience continue?

    January renewals continued easing along with increased capacity and rate reductions globally

    Softening market under pressure

    The scale of the LA wildfires raises questions about the potential for flow-on impacts to reinsurer risk appetite and to the expectations of further softening at the 1 July renewals for the Australian market.

    Adding to the concern is the sheer size of this event – with estimates of economic loss generally in excess of USD $100 billion and of insured losses up to USD $45 billion – compounded by continuing uncertainty. This includes doubt about the ultimate cost to be borne by insurers (much of the areas affected by the wildfires were underinsured or had no coverage), whether the fire constitutes multiple events, subsequent losses attributable to the fire (e.g. burnt areas having a greater propensity for landslides) and the pace of rebuilding.

    What the industry has to say

    Reinsurance is a major expense for Australian property insurers, accounting for approximately 30 per cent of premium revenue over the 12 months to 31 December 2024. With this in mind, we interviewed reinsurers and brokers to explore their view on the possible impact of the wildfires on the next renewals at 1 July in Australia.

    Overall, there was general agreement that, in isolation, the wildfires were not likely to affect the trend of increasing risk appetite and capacity we’ve seen over the past year. Key factors supporting this view were:

    • While rates softened over the past year, property reinsurance rates are at an all-time high, providing some level of buffer against a bad start to 2025, with plenty of capacity available at the 1 January renewals
    • The 2023 market recalibration led to significantly increased rates and a shift to insurers retaining more risk, reducing the burden on reinsurers.

    Too early to predict an impact?

    Some insurers and brokers we spoke to believed it was too early to predict an impact, with costs and cleanup ongoing as well as uncertainty about catastrophic activity for the rest of the year.

    Others indicated the wildfires may slow the pace of rate reductions, while further interviewees said while the wildfires in isolation would not affect market momentum, subsequent events throughout the year may.

    In isolation, the wildfires were not likely to affect the trend of increasing risk appetite and capacity we’ve seen over the past year.

    APRA mitigation efforts

    The Australian Prudential Regulatory Authority is currently consulting on adjustments to its reinsurance settings. In seeking industry feedback (which closed on 17 February), APRA aims to address general insurer challenges to accessing appropriate, cost-effective reinsurance, with proposed changes to the capital adequacy prudential standard GPS116 that may reduce the amount of reinsurance they need to purchase and make Insurance Linked Securities a more attractive option for insurers.

    Where to from here – this year and beyond

    Many questions remain as to how the wildfires will actually impact 1 July renewals. In our view, experience to date points towards a continued softening market, but perhaps not to the level expected prior to the wildfires. Back home, communities and insurers are starting to assess the damage of ex-Tropical Cyclone Alfred, which may impact reinsurance appetite for Australian exposure at the next renewal.

    In the meantime, all eyes are on the 1 April Japanese renewals, which will be the first major renewal to factor in the wildfire impact. Watch this space.

  • NSW Department of Communities and Justice releases Taylor Fry report

    Improved child protection outcomes are among several findings in Taylor Fry’s evaluation of a key government program to strengthen the lives of children, young people and families experiencing or at risk of vulnerability.

    Further research in the report – Targeted Earlier Intervention (TEI) Evaluation – released by the NSW Department of Communities and Justice (DCJ), also shows increased sense of belonging in the community, empowerment and self-determination, and health of children and young people.

    Co-authored in partnership with Social Ventures Australia and Gamarada Universal Indigenous Resources, we found improvements as well as economic benefits in safety outcomes. This means there was a reduction in concern and risk of significant harm reports as well as exits from out-of-home care. The improvements in safety outcomes translate to $92 million in annual benefits at a minimum.

    The report found better safety outcomes with increased access to services early in life and need

    The report, Targeted Earlier Intervention (TEI) Evaluation, focuses on the outcomes and economic evaluation of the TEI program. The program aims to prevent the escalation of risks associated with child abuse and neglect by increasing access to services at the most impactful time – early in life and early in need. It also aims to reduce the number of children exposed to the child protection system.

    Other findings in our evaluation include:

    • The proportion of Aboriginal clients who have received services from Aboriginal and/or Torres Strait Islander Community-controlled Organisation (ACCO) providers has increased over time since 2020-21
    • However, the proportion of funding provided to ACCO providers in 2022-23 was 7.7%, which is below DCJ’s target of 30% in Aboriginal-led early intervention programs
    • Participation in TEI did not appear to reduce the rate of children entering out-of-home care
    • Participation in TEI led to increased referrals to key service areas, such as housing, which shows that TEI services are connecting clients to services they need.

    Among our seven recommendations detailed in the report, we propose the DCJ increase funding and capacity of Aboriginal and/or Torres Strait Islander Community-controlled Organisations, focus on increasing TEI access in high population-growth and remote areas, and increase flexibility in service provision and provider awareness.

    This Final Report builds on our previous Interim Report, which focused on more qualitative aspects of the evaluation.

    For more details, read the Final Report in full.

  • RADAR FY2024 New Zealand Snapshot

    Escalating premiums, the need for better adaptation responses and a growing cyber market are the big themes capturing insurers’ attention across Aotearoa – all amid a market grappling with increasing regulation. In RADAR FY2024 New Zealand Snapshot, we draw on the most up-to-date data combined with our deep industry insight to find meaning and help market players navigate the future.

    Impacts of benign weather  

    The cascading effects of benign weather in FY2024, following particularly severe natural perils in 2023, include large premium hikes and substantial insurer profits.

    Reinsurance a major driver

    Reinsurance costs are a major factor driving the volatile environment, with reinsurers reacting to the previous year’s losses by raising premiums – and the limits at which reinsurance cover starts – effectively passing on their overheads to insurers.

    The expectation is for reinsurance rates for property risks to remain at current levels, given the 2024 US hurricane season resulted in two significant events. For New Zealand policyholders, this suggests no substantial relief from insurance premiums due to international factors such as reinsurance costs, for the foreseeable future.

    Affordability and transparency top of mind

    As prices rise, affordability continues to exert pressure on New Zealanders – premiums are up 20 per cent for all personal insurance lines over the past year, leading to calls from consumer advocates for more transparency on how insurance premium prices are calculated. Home and contents policies have been hit hardest, with the overall percentage rise for personal lines in addition to earlier increases of 15% for home and 10% for contents in 2023.

    Rate hikes, particularly on home policies, have highlighted the need to improve adaptation responses

    Adaptation key

    These challenges highlight the need to improve adaptation responses to the risks arising from natural disasters, particularly as the impact of climate change exacerbates the risks. Efforts are already underway to advance progress. The Climate Change Commission and New Zealand’s Parliament have released reports to variously address areas requiring urgent action in managing costs, providing appropriate resources and ensuring market ability to contain risk. The insurance industry will play a part, but significant input from government is vital.

    Regulators focus on customer treatment

    Regulators are increasingly focusing on insurers and the fair treatment of customers. Among a raft of changes, the RBNZ is currently revising the Insurance (Prudential Supervision) Act 2010 (IPSA). Industry expects the revised IPSA will enable the RBNZ to undertake more proactive and intensive supervision of insurers. In this environment, it will be crucial for insurers to continue placing policyholders front of mind in every decision they make for their business.

    In this environment, it will be crucial for insurers to continue placing policyholders front of mind in every decision they make for their business.

    Cyber growing, but take-up slow

    On cyber, while New Zealand shares only a fraction of the global cyber insurance market – about NZD $45 million of a total NZD $26 billion in gross written premium – the local cyber market is growing, albeit slowly. Only 8 to 10 per cent of New Zealand businesses are estimated to hold cyber policies, significantly less than peer countries, and this figure is even lower for small and medium-size enterprises.

    Cyber risk continues to be a focus for regulators and policymakers in New Zealand – the RBNZ and the New Zealand Government among entities implementing new rules with implications for all general insurers.

    We unpack all these key movements, trends and more in RADAR New Zealand FY2024 Snapshot, as the industry seeks solutions not only to meet its challenges head on but to bolster resilience and thrive.

  • Cyber update – protection gap widens for SMEs

    In a new dialogue paper for the Actuaries Institute, Taylor Fry Principal Win-Li Toh and ESG Advisor Sarah Wood, along with co-author Dr Michael Neary of DXC Technology, reveal most small and medium enterprises are not well prepared for a cyber incident.

    The paper, Cyber Protection Gap Widens for SMEs, follows two years of several high-profile cyber incidents, an uptick in reported cybercrime, and a raft of government responses and regulation tightening.

    Through research and interviews with industry stakeholders, the authors explore the major cyber challenges, impacts and what can be done for SMEs in corporate Australia. It finds that compared to big corporates SMEs have not had similar bandwidth or resources to devote to their cyber security.

    SMEs are vital to the Australian economy and the consequences of an attack could be far reaching

    The paper revisits the rapidly shifting threat landscape and how it’s changed since the Institute’s 2022 report, Cyber Risk and the Role of Insurance, also by Win-Li and Michael, with Taylor Fry Director Ross Simmonds.

    In this latest release, the authors advise that “bridging the cyber protection gap for SMEs will require continued (and relentless) collaboration and effort across government and the insurance industry, as well as within the small business community and the providers of technology solutions that support them”.

    They offer five recommendations towards reducing the gap:

    1. Continue to strengthen national cyber defences
    2. Evaluate and scale up education and upskilling initiatives
    3. Make it easy for SMEs to show they take cyber seriously
    4. Consider SMEs’ unique cyber challenges in the upcoming round of Privacy Act changes
    5. Keep the dialogue open between government, the insurance industry and small business.

    Visit the Actuaries Institute website to read the paper in full.